
Daily Sector Snapshot — 9/9/26
Financials Fall Across the Board
Financials fell 1.4% yesterday, and there was almost nowhere for investors to hide within the sector. W.R. Berkley (WRB) was the only stock to finish higher, gaining 0.91%, compared to 75 stocks that declined. That put daily net breadth below -97% for the first time since 3/27. As widespread as the selling was, the sector’s decline was relatively modest by that standard. Since 1990, there have been 230 days with net breadth of -97% or worse, and yesterday’s performance was the 13th best.

Before yesterday, Financials had gone 111 trading days without net breadth of -97% or worse. As shown below, that was the longest stretch since a 144-trading-day streak ended in December 2023.

Financials gained 21.2% during the latest 111-day streak. The table below shows how the sector performed during and after previous streaks lasting at least that long. Across the 18 prior occurrences, near-term returns have been weak. The sector has averaged a decline of 3.1% over the following week, with gains just 16.7% of the time. A month out, the average decline has been 1.9%, and fewer than three in ten returns have been positive.

Further out, results have improved. Average returns turn positive at three months, although the sector has been higher only a little more than half the time. A year later, Financials has averaged an 11.4% gain, with positive returns in 77.8% of occurrences.
You can find more sector research like this in Bespoke’s Daily Sector Snapshot.
Read about Bespoke’s premium membership options to find out how to receive our Sector Snapshot in your inbox daily.
Chart of the Day – Will a Foldable Flop?
Bespoke’s Morning Lineup – 9/9/26 – Oil Keeps Going, Bitcoin Stalls
See what’s driving market performance around the world in today’s Morning Lineup. Bespoke’s Morning Lineup is the best way to start your trading day. Read it now by starting a two-week trial to Bespoke Premium. CLICK HERE to learn more and start your trial.
“The two most powerful warriors are patience and time.” – Leo Tolstoy
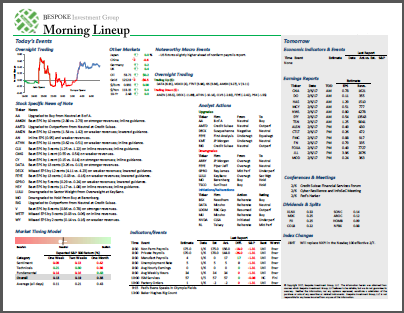
Below is a snippet of commentary from today’s Morning Lineup. Start a two-week trial to Bespoke Premium to view the full report.
Rising crude oil prices are weighing on equity prices this morning, and the picture has weakened ahead of the opening bell. The S&P 500 is on pace to open down 0.4% while the Nasdaq trades down more than 0.5%. Treasury yields are little changed, with the 10-year trading at 4.8% ahead of today’s auction. As already mentioned, crude oil is trading higher, and this morning’s 3% gain has WTI trading above $95 per barrel. Gold is fractionally higher, and Bitcoin is up over 1% and above $79K.
Asian stocks were mixed overnight. The Nikkei and Hang Seng both experienced modest losses of less than 0.3%, while the Kospi rallied 1.4%. In China, August CPI increased 0.4%, which was slightly higher than expected (0.3%) and was the first positive m/m reading since April. In South Korea, the unemployment rate fell from an already low level of 2.8% down to 2.7%.
European stocks are facing steeper losses this morning after Brent crossed the psychologically important $100 level. The STOXX 600 is down more than 1%, and every major benchmark is also down at least 1%, with Spain and France leading the way lower with declines of at least 2%.
There’s no major economic data on the calendar today, but at 1 PM Apple (AAPL) will hold its new product announcement where the foldable iPhone is widely expected to be unveiled. In addition to that product announcement, we’re still in the thick of conference season, so be on watch for isolated tape bombs throughout the day.
Just as Brent topped $100 for the first time since July, WTI is at its highest levels since June this morning (more on that in the commentary section of today’s report). No matter what CPI is on Friday, if crude remains at these levels or even climbs from here, there’s only one direction CPI, and ultimately interest rates, will go from here.

While WTI remains well off its highs from earlier in the year, heating oil is on pace for a new closing high. At $4.73 per gallon, the price is up over 50% from its low in June.

Shifting focus away from the energy markets, Bitcoin prices had a big jump in August right around the time that Treasury Secretary Bessent announced the revised Treasury buyback program. Since that spike higher, though, prices have stalled out just below $80K. That resistance level also coincides with the spring peak when that rally stalled out right at the 200-DMA.
This time around, Bitcoin is well above its 50- and 200-day moving averages. In fact, those moving averages just experienced their first golden cross, where the rising 50-DMA crossed through the rising 200-DMA, since May 2025.

Technicians consider a golden cross to be a positive technical formation, but they don’t always play out that way. The long-term chart of Bitcoin below shows each golden cross with a red dot, and as shown, most golden crosses have been followed by gains.

Start a two-week trial to Bespoke Premium to continue reading today’s full Morning Lineup.
The Closer – Equal Weight Test, Buffer ETFs, Credit – 9/8/26
Log-in here if you’re a member with access to the Closer.
- While the equal weight S&P 500 has pulled back to test its 50-DMA, mega-caps remain consolidated.
- Buffer ETFs have gained traction in recent years with inflows of $8.8 bn in the past year alone.
- Today’s release of the Fed’s monthly estimates of net consumer credit showed the largest MoM uptick in non-revolving credit since 2023.

See today’s full post-market Closer and everything else Bespoke publishes by starting a 14-day trial to Bespoke Institutional today!
Daily Sector Snapshot — 9/8/26
Matrix of Economic Indicators – 9/8/26
Our Matrix of Economic Indicators provides a concise summary analysis of the US economy’s momentum. We combine trends across the dozens and dozens of economic indicators in various categories like manufacturing, employment, housing, the consumer, and inflation to provide a directional overview of the economy.
To access our newest Matrix of Economic Indicators, start a two-week free trial to either Bespoke Premium or Bespoke Institutional now!

Chart of the Day – Is Nvidia (NVDA) Even a Semiconductor Stock Anymore?
Back to Work and Back in the Red
The S&P 500 is off to another weak start after Labor Day, down about 0.4% as we write this. If the decline holds through the close, it would mark the tenth straight year that the index has fallen on the day after the holiday. The last gain was in 2016, when the S&P 500 rose 0.30%.

Since 1945, the day after Labor Day has averaged a decline of 0.14%, with gains 49% of the time. Over the last ten years, though, the average decline has been a much larger 0.81%. That recent weakness has often extended beyond the first day back. The S&P 500 has declined in seven of the last ten Labor Day weeks, averaging a drop of 0.80%. Performance over the rest of September, historically the weakest month of the year, has been evenly split between gains and losses, but the average return has been negative at -1.17%, although the median decline is a much more modest 0.05%. September declines of more than 5% in 2021, 2022, and 2023 weighed on that average.

Through year-end, the picture has been more positive. The S&P 500 has rallied over the post-Labor Day period in eight of the last ten years, averaging a gain of 3.57% and a median gain of 5.36%. The only declines came in 2018 and 2022, with 2018’s 13.60% drop standing out as the weakest by far. Those results are broadly consistent with the longer-term record. Since 1945, the index has averaged a 3.23% gain over the rest of the year, with positive returns 73% of the time.

Bespoke’s Morning Lineup – 9/8/26 – Back to the Grind
See what’s driving market performance around the world in today’s Morning Lineup. Bespoke’s Morning Lineup is the best way to start your trading day. Read it now by starting a two-week trial to Bespoke Premium. CLICK HERE to learn more and start your trial.
“If people knew how hard I had to work to gain my mastery, it would not seem so wonderful at all.” – Michelangelo
Below is a snippet of commentary from today’s Morning Lineup. Start a two-week trial to Bespoke Premium to view the full report.
It could be worse. US equity futures are down across the board this morning as traders return to work after the long holiday weekend. Dow futures are down 0.8%, but the damage is much less in the S&P (-0.3%), while Nasdaq futures are barely lower (-0.1%) as the picture has been improving all morning. Why could it be worse? That’s because crude oil keeps rising, with WTI trading nearly 3% higher to $94 per barrel. Along with rising crude oil, energy products are also trading higher off already high levels.
Energy prices can’t keep rising without impacting the market, and at some point even a tame inflation report later this week may not mean much if crude oil prices remain in the mid-90s, approaching triple digits.
Outside of equities and energy markets, Treasury yields are little changed this morning, gold is down nearly 1%, and Bitcoin is down over 1%.
Asian equities were mostly lower overnight except for onshore Chinese stocks, which rallied modestly. The Nikkei fell 1.7% while South Korea fell a more modest 0.6%. In economic data, Japan’s Q2 GDP report showed stronger-than-expected growth at 0.4% q/q versus forecasts for an increase of 0.3%, while South Korean GDP was right in line with expectations at 0.6%.
European equities are little changed, with the STOXX 600 down less than 0.1% and no major country’s benchmark down more than half a percent as a rate hike at its policy meeting later this week is a near certainty.
In the US today, it’s a quiet morning with NFIB Small Business Sentiment being the only report on today’s calendar. That reading for August declined more than expected, but the NFIB’s chief economist Bill Dunkelberg noted that “Uncertainty remains elevated among small business owners as they face a mixed set of challenges”. Besides that report, we’re in the heart of conference season, so be on guard for companies issuing not-so-rosy comments at some of these meetings across Wall Street this week. Looking forward, while today’s calendar is quiet, the PPI and CPI reports on Thursday and Friday will be main events.
Back in late July, as the dollar was breaking out to multi-year highs versus the Japanese yen, authorities intervened to stop the slide. The yen immediately rallied, taking the cross versus the dollar down to its 200-DMA for the first time since last fall. After the initial rally, though, the yen slowly started weakening again, leading some to question the move’s efficacy.
The last week may have been quiet for US markets, but it’s been a big move in the yen. The currency has resumed its rally versus the dollar as market participants increasingly expect the BoJ to raise rates at its meeting next week. This morning, it’s trading at its strongest levels relative to the dollar since February. As the WSJ noted this morning, “Bessent’s Yen Bet Is Paying Off—for Now”.

While the yen is rallying, the Nikkei 225 has been under some pressure. The index peaked in mid-June and has been trending lower ever since. The index briefly peaked its head above the 50-DMA for about a week in early to mid-August, but quickly lost momentum. On Monday, the Japanese benchmark made another attempt to reclaim that level, but reversed lower overnight.

The picture for European stocks looks similar. The STOXX 600 peaked in early August, but it too has been trending with weaker momentum for the last few weeks, and it now also finds itself trading below the 50-DMA.

Moving closer to home, the S&P 500 went into Labor Day weekend trading above both its 50- and 200-DMAs, but it too has been trading in a sideways range since its high on August 13th. Based on where futures are trading this morning, last week looks to have been the second-lowest high since that peak in a very tight downward-sloping range of less than 3%. Not a terrible setup, but not the momentum bulls want to see heading into the weakest month of the year.

Start a two-week trial to Bespoke Premium to continue reading today’s full Morning Lineup.